Save on car insurance in Clarenville.
We’re one of the largest independent brokers for auto insurance in Clarenville. We specialize in auto insurance. With a simple online quote or a quick call, you will get quotes from up to eight insurance companies. And with savings of up to 30%, you’ll be on the road with Clarenville’s best auto protection and benefits. That’s a promise.
Clarenville, limitless potential.
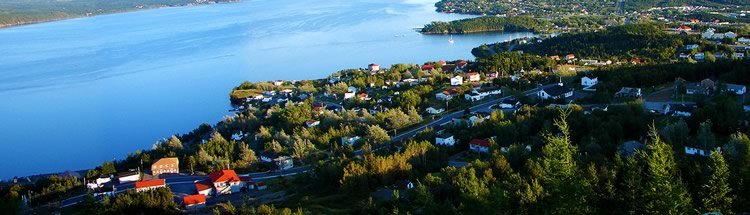
A thriving town nestled in an abundance of natural beauty, Clarenville is a hub of business and urban convenience. The residents enjoy the comforts of modern life without losing the small-town character and community spirit. Just a few minutes off the Trans-Canada Highway, it’s the perfect location for travellers heading across the province and for residents to travel to larger centres such as St. John’s and Gander. Your insurance can be as unique as your route. At Munn Insurance you can find the most competitive rates for auto insurance in Clarenville and save while you’re doing it.
Driving in Clarenville – Tips to keep you on the road.
DRIVING BY.
Clarenville is situated just minutes off the Trans-Canada Highway. This means a quick reduction in speed for highway travelling. From the intersection of Memorial Drive to Manitoba Drive, the speed is reduced from 100km to 70km.
FOG MEANS FOCUSED.
Newfoundland means fog, and Clarenville is no exception to the towns that can be hit by this extremely dangerous weather condition that is often underplayed. Drivers should slow down as driving at normal speeds in fog can be very dangerous. Slowing down means more time to react to traffic stops and potential hazards. Also, motorists should avoid using high-beam headlights in fog as fog consists of tiny water droplets that spread and reflect light. Low-beams should be used to help vehicles to be visible to one another. And last, always remain focused. Turn down the radio, stop conversations and keep attention on the road.
TAKE A CAB.
Newfoundland has severe impaired driving regulations to help keep all residents safe. As of 2017, any driver whose licence was suspended after an impaired driving conviction will be required to enter a mandatory ignition interlock program as a condition of reinstatement. As well, anyone 22 years and younger are required to maintain a zero-blood alcohol content while driving. Not a risk you want to take. There are three cab companies in Clarenville and Shoal Harbour ready to take you wherever you need to go.
HAND FREE AT ALL TIMES.
Fines for using a cell phone while driving are high in the province of Newfoundland, and the RNC are extremely vigilant in the Town of Clarenville. The current penalty is 4 demerit points with fines ranging from $350 to $1000.
A few facts about car insurance in Clarenville.
- The average age of auto insurance policyholder in Clarenville is 34
- The average age of drivers in Clarenville is 46
- The number of accident claims in Clarenville in 2018 was 1000
- The top automotive brands we insure in Clarenville are Ford, Chevrolet, Honda, Toyota, Hyundai, Dodge, GMC
- 60% of people in Clarenville drive Cars
- 40% of people in Clarenville drive Truck
Facts and myths about Clarenville.
FACTS
The Town acts as a natural gateway to the Discovery Trail, extending down the Bonavista Peninsula to Trinity and Bonavista, the reputed site of the first landing of European explorer John Cabot.
Clarenville is centrally located and within two hours’ driving time of 70% of the province’s population.
Clarenville has the only ski resort east of Corner Brook, White Hills Ski Resort.
The Town held the 1994 Newfoundland Winter Games, the 1997 National Under 17 Men’s Softball Tournament and in November 2010 hosted two games of the Four Nations Cup.
MYTHS
Health services in Clarenville are managed by Eastern Health. Clarenville has five health care facilities, the Dr. G.B. Cross Memorial Hospital, Dr. Albert O’Mahoy Memorial Manor, Coish Place, Protective Community Care Residence and DM Brown Building.
Clarenville has a variety of recreational facilities and activities. From sports centres, an event centre, multiple parks and trails to a farmer’s market, a marina and multiple historic sites, there is something for everyone.
The Town has an elementary, middle and high school. Clarenville is also home to the College of the North Atlantic Clarenville Campus that offers a variety of certificate and diploma programs.
Clarenville is situated within two hours’ drive of 70% of Newfoundland’s population.
We do the shopping. You get the savings.
Newfoundlanders love choice. And they love saving too! At Munn Insurance, we deliver on both. As an independent insurance broker, we shop our extensive network of insurance partners to provide our Newfoundland customers with the best coverage at the best rate. Some of the insurance companies we search for our customers include:
How Munn Insurance saves you money.
We work for you – that’s what an insurance broker does. We shop the market on your behalf, so Munn insurance can offer you the most access to the best discounts from our insurance partners.
- Bundling (Auto + Home Discount)
- Multiple Vehicle Discounts
- Experienced Drivers Discount
- Safe Drivers Discount
- Claims-Free Discount
- Loyalty Discount
- And Many More
Combine your home and car policies and save.
With Munn Insurance, home and auto policies are better together. It means extra savings and additional coverage. So combine them both and receive a discount on both. That’s like a double discount!
Combining also gives you the extra convenience of aligned renewal rates and less paperwork.
You can combine your auto policy with any Munn Insurance home policy for the following dwelling types:
- Private Homes
- Condos
- Tenants
- Cabins/Cottages
- Rented Dwellings
Special discounts and savings with a Munn Insurance Group policy.
We recognize the value groups provide to Newfoundland communities. First Responders, Health Care Professionals, Alumni Associations, Educators and Instructors all play a vital role in helping others across the Island. They give so much, and we’re happy to give back. Munn Insurance Preferred Groups in Newfoundland are able to take advantage of special discounts and many extra-valuable benefits.
- Special Group Discounts
- Mortgage & Real Estate Assistance
- 0% Insurance Financing
- Home Repair Assistance
- Legal Assistance
- Health Assistance
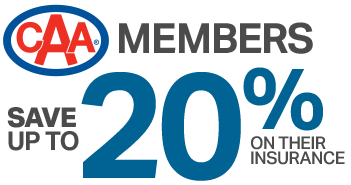
- CAA Members can SAVE up to 20% on Auto and Home Insurance
- Access to multiple insurance markets; knowing you get the best coverage at the best rate
- Confidence and security of being a member of a preferred group
- Local, fast and efficient 24/7 Claims Service
- Legal Assistance
- Health Assistance
Get Newfoundland’s best leisure vehicle protection.
Newfoundlanders love their leisure time and their leisure vehicles. MyRide Leisure Insurance from Munn Insurance is the most competitive, comprehensive leisure vehicle insurance available in Newfoundland. Whether it’s your ATV, motorhome, motorcycle – or any of your leisure vehicles – A Munn policy offers more protection and value than any other program you’ll find.
- Boat and Watercraft
- ATV
- Snowmobile
- Classic Cars and Auto
- Motorhome, RV and Trailer
- Motorcycle
Car insurance laws in Clarenville.
Clarenville drivers must be in possession of legally determined minimum insurance coverage to drive on our roads. These minimum limits have been enacted to ensure drivers are financially responsible if an at-fault accident occurs.
Current limits for auto insurance in Clarenville are:
- $200,000 in liability coverage per accident
- Uninsured and unidentified motorist coverage
Clarenville drivers are not required to carry accident benefits coverage, although most do choose to buy this coverage, which includes coverage for medical payments, disability coverage, and death benefits coverage. This type of insurance is mandatory in other provinces. Many drivers in Newfoundland also opt to increase their liability coverage to limit risk and financial exposure.
There are also other optional coverages that can be purchased. These include comprehensive and collision coverage to protect in the event of an at-fault accident or non-accident scenario such as theft.
Clarenville car insurance – your questions answered.
Our Latest Advice
9 Things to Consider Before Your Commercial Auto Insurance Renewal
Your commercial auto insurance renewal should be more than a quick look at the new premium and a decision to renew.
A lot can change in a business over the course of a year.
You may have bought or sold vehicles. Drivers may have joined or left the company. Your vehicles may be travelling farther, carrying different equipment or being used for different types of work. You may have taken on new contracts, experienced a claim or started thinking about adding more vehicles.
Your insurance needs to keep up.
And before you even get into the details of the policy itself, there is another important question to ask: are you getting the advice, support and service you need from your broker?
A good commercial auto renewal should involve more than paperwork. It should be a chance to review your business, your vehicles, your drivers, your coverage, your insurer and what may be changing next.
Here are nine things every business owner in Newfoundland and Labrador and Nova Scotia should look at before your next commercial auto insurance renewal.
1. Are You Getting the Support and Service You Need From Your Broker?
Your commercial auto insurance is only as useful as the advice and support behind it.
A good broker should do more than send you a renewal and ask whether you want to proceed.
They should understand your business, your vehicles, your drivers and how your operation is changing. They should be available when you have questions, help you understand your coverage and make sure important changes are addressed as they happen.
Before renewal, ask yourself:
- Does my broker understand my business?
- Do we speak during the year, or only at renewal?
- Do they help me think ahead about changes to vehicles, drivers or operations?
- Do they explain my coverage and identify potential gaps?
- Do they help me understand why my premium has changed?
- Do they review available markets and alternatives when appropriate?
- Do I get timely answers when I have questions or need help?
- Do I feel like they are actively managing my account rather than simply processing my renewal?
For a business that depends on its vehicles every day, your broker should be a resource — not just someone who sends an invoice once a year.
If you are not getting the advice, responsiveness and attention your business deserves, your commercial auto renewal is a good time to consider whether you have the right broker.
2. Make Sure Your Vehicle List Is Accurate
Start with the basics: what vehicles does your business actually have today?
Over the course of a year, businesses buy vehicles, replace them, sell them and move them into different roles. In NL and NS, that might mean adding a work truck for a new contract, taking a seasonal vehicle off the road or replacing equipment after a hard winter.
Before renewal, review every vehicle on your policy and confirm:
- Year, make and model
- Vehicle identification number
- Ownership
- Vehicle value
- Whether it is financed or leased
- Where it is normally kept
- Whether it is still being used
- Any trailers or other vehicles that also need to be considered
If you sold a vehicle, make sure it has been removed. If you bought a replacement, make sure the information is correct. If a vehicle has been modified or fitted with specialized equipment, tell your broker about that too.
This is also a good time to think ahead. If you know you are buying another truck or van in the next few months, discuss it during the renewal review rather than waiting until the vehicle arrives.
Your commercial auto policy should reflect the vehicles you actually own and operate — not the vehicles you had a year ago.
3. Review Everyone Who Drives Your Vehicles
The vehicles are only part of your commercial auto risk. The drivers matter too.
Insurance companies can consider licence status, driving experience, convictions, accidents and claims when assessing a commercial auto risk.
Before renewal, review your regular drivers and ask:
- Are all current drivers properly identified?
- Have any employees left?
- Have new drivers been added?
- Have driving responsibilities changed?
- Are driver’s licences current and appropriate for the vehicles being operated?
- Have there been new convictions or accidents?
- Are you periodically reviewing employee driving records?
If someone who used to drive occasionally is now behind the wheel every day, that is worth discussing. Likewise, if a driver with a poor record has left the company, your broker should know that too.
Make sure the drivers your insurer is evaluating are the drivers actually operating your vehicles today.
4. Confirm How Each Vehicle Is Being Used
Two identical pickups can present very different insurance risks depending on what they do every day.
One may be driven locally to customer meetings. Another may travel between job sites across NL or NS carrying tools, hauling materials and towing a trailer.
Before renewal, review how each vehicle is actually being used:
- What type of work does it perform?
- Does it travel between job sites?
- Does it make deliveries?
- Does it carry tools or equipment?
- Does it transport goods?
- Does it tow a trailer?
- Does it transport customers or passengers?
- How far does it typically travel?
- Has its operating territory changed?
- Has annual mileage changed significantly?
- Is it used seasonally or year-round?
If your operations have changed, your insurance information should change with them. Don’t renew based on last year’s description of your business if this year’s business looks different.
5. Look at Your Claims History — and What You’ve Done About It
Your commercial auto renewal is also a good time to look back at what happened during the year.
Did you have any accidents? Vehicle thefts? Physical-damage claims? Near misses that exposed a potential problem?
Look beyond simply counting claims — ask what you can learn from them.
- If you experienced several backing accidents, could additional driver training help?
- If vehicles were being damaged while parked, could you change where they are stored?
- If theft has become a concern, are there additional security measures worth considering?
- If one driver has been involved in repeated incidents, does that need to be addressed?
A good risk-management approach might include:
- Driver screening and training
- Preventive vehicle maintenance and regular inspections
- Distracted-driving and winter-driving procedures
- Accident-reporting procedures
- Telematics, where appropriate
Don’t just tell your broker what claims happened. Talk about what your business has done to help prevent them from happening again.
6. Review Your Liability Limits and Contractual Requirements
Commercial auto insurance is not only about repairing damaged vehicles. A serious accident can also result in significant liability if another person is injured or their property is damaged.
That makes your third-party liability limit an important part of the renewal conversation. Don’t simply assume the limit you selected several years ago is still appropriate.
Consider whether:
- Your business has grown
- Your vehicles are travelling more
- You have added drivers
- You are operating larger or heavier vehicles
- Your contractual requirements have changed
- Customers or general contractors are requiring higher limits
- Landlords or project owners have specified minimum insurance requirements
If you are bidding on a new contract — common in the construction, trades and energy sectors across NL and NS — bring the insurance requirements to your broker before you sign it.
The legal minimum and the amount of protection appropriate for your business are not necessarily the same thing.
7. Review Your Deductibles and Physical-Damage Coverage
Your vehicles change in value over time. Your ability to absorb a loss may change too. That makes renewal a good time to revisit your deductibles and optional physical-damage coverage.
Review whether you currently carry:
- Collision
- Comprehensive
- All Perils
- Other optional physical-damage protection
Then consider each vehicle individually. The coverage that makes sense for a new $75,000 pickup may be different from what makes sense for an older vehicle with a substantially lower value.
The same applies to deductibles. A higher deductible can sometimes reduce premium because the business is agreeing to assume a larger portion of a loss — but saving money on premium does not help if the deductible creates a financial problem when you actually need to make a claim.
Ask: if something happened to this vehicle tomorrow, could the business comfortably absorb the amount we have chosen to self-insure?
The goal is to find the right balance between premium and protection.
8. Look Beyond the Vehicle Itself
A commercial auto renewal is a good opportunity to think about the things connected to your vehicles that may not automatically be covered by the automobile policy.
Consider what your vehicles carry and tow:
- Tools and specialized equipment
- Inventory, building materials or customer property
- Utility or enclosed trailers
- Machinery being transported
- Other valuable business property
Insuring the truck or van does not necessarily mean everything inside it or behind it has the protection you expect. This is especially important for contractors and trades businesses in NL and NS where a work vehicle may contain thousands of dollars worth of tools and equipment.
Also think about vehicles your business doesn’t own. Do employees use personal vehicles for business errands, customer visits or deliveries? Does your company rent vehicles?
Depending on your operation, additional coverage such as non-owned automobile liability may need to be considered.
Your renewal discussion should include what you drive, what you carry, what you tow and what other vehicles are being used on behalf of the business.
9. Review the Price — and Whether Your Current Insurer Is Still the Right Fit
Once you know the information and coverage are right, look at what you are paying.
Has your premium changed? If so, why? Has your claims experience changed? Are there discounts or credits you may now qualify for?
Different insurance companies look at commercial auto risks differently. One insurer may be particularly competitive for contractors, another for service businesses, another for smaller fleets. That is why your renewal should include a discussion about whether the current insurer still offers the right combination of coverage, price, underwriting flexibility, claims service and fit with your type of business.
Depending on the insurer and your eligibility, there may also be opportunities such as:
- Multi-vehicle discounts
- Conviction-free discounts
- Commercial package or loyalty discounts
- Fleet or loss-prevention programs
- Telematics programs for qualifying fleets
And if your business has grown, ask whether the way your vehicles are insured is still appropriate. A business that started with one vehicle may now have four. Don’t assume your current insurer or policy structure remains the best choice simply because it worked last year.
Don’t Wait Until Your Renewal Documents Arrive
A good commercial auto renewal process should start before the renewal documents land in your inbox.
Ideally, you should be talking to your broker during the policy term about changes in your business and then having a more detailed review well before renewal. A mid-term discussion gives you an opportunity to talk about things that have already changed — and what may be coming next.
You may be planning to buy more vehicles, replace older ones, hire more drivers, expand into another area, take on a significant contract or grow toward a full fleet. Talking about those plans early gives your broker time to help you prepare — and more time to properly compare alternatives if your current insurer is no longer the best fit.
Don’t just wait for the renewal, look at the premium and sign. Use the renewal as an opportunity to make sure your commercial auto insurance still fits your business.
Your Commercial Auto Renewal Checklist
Before your next renewal, make sure you can answer these nine questions:
- Are we getting the advice, support and service we need from our broker?
- Are all of our vehicles listed correctly?
- Are our drivers and their information current?
- Does our policy accurately reflect how our vehicles are being used?
- What does our claims experience tell us, and what have we done to manage risk?
- Are our liability limits still appropriate for our business and contracts?
- Do our deductibles and optional coverages still make sense?
- Have we properly considered our tools, equipment, trailers and non-owned vehicles?
- Is our current insurer, policy structure and price still the right fit?
If you can’t confidently answer all nine, there is something worth discussing with your broker.
Commercial Auto Renewal Coming Up? Talk to Munn Early.
At Munn Insurance, we don’t believe a commercial auto renewal should simply roll over from one year to the next. We work with businesses across Newfoundland and Labrador and Nova Scotia — contractors, trades, service companies, healthcare providers, energy sector operators and more — and we take the time to understand your operation, not just your vehicles.
As an independent insurance broker, Munn can compare commercial auto insurance options from multiple insurance companies to help make sure you continue to have the right coverage at the right value. And if you’re not getting the service, advice or attention you need from your current broker, we’d be happy to take a second look.
Whether you have one work vehicle or a whole fleet, talk to Munn well before your next commercial auto insurance renewal.
Visit: munninsurance.com/business/commercial-auto-insurance-for-atlantic-canada/
Call: 1-855-726-8627
Don’t just renew. Review. Get the right coverage. Get the right value.
How Much Does Landlord Insurance Cost in Newfoundland and Labrador and Nova Scotia?
If you own a rental property, or are thinking about [...]
Are You Paying Too Much for Commercial Auto Insurance? 7 Ways to Help Lower Your Cost
Commercial Auto Insurance is an important cost of doing business [...]
Fall Checklist for Landlords in Newfoundland and Labrador and Nova Scotia
Fall is one of the best times for landlords to [...]