How Much Does Landlord Insurance Cost in Newfoundland and Labrador and Nova Scotia?
If you own a rental property, or are thinking about buying one, there is a good chance you have wondered:
How much does landlord insurance cost?
The short answer is that there is no single price for landlord insurance.
The cost of landlord insurance in Newfoundland and Labrador and Nova Scotia depends on the property you are insuring, where it is located, how it is used, the coverage you choose and a number of other factors.
A newer single-family rental home in St. John’s will not necessarily cost the same to insure as an older duplex in Halifax. A landlord with one rental property may also have very different insurance needs from someone with several properties or multiple units.
The best way to know what landlord insurance will cost for your property is to get a quote based on the actual details of the rental.
But it helps to understand what goes into that price.
What Determines the Cost of Landlord Insurance?
Insurance companies look at a number of factors when determining what it will cost to insure a rental property.
Some of the most important include:
- Location
- Cost to rebuild the property
- Type and size of the building
- Number of rental units
- Age and condition
- Roof, plumbing and electrical systems
- Type of heating
- How the property is occupied
- Claims history
- Coverage selected
- Deductible
- Fire protection
- Water and other location-specific risks
- Whether the property is occupied or vacant
Let’s look at some of these in more detail.
1. Where Is the Rental Property Located?
Location can have a significant impact on insurance cost.
Insurers may consider factors such as:
- Local claims experience
- Exposure to severe weather
- Water and flood-related risk
- Proximity to fire protection
- Distance from a fire hydrant or fire station
- Crime and theft experience
- Whether the property is urban or rural
Two similar rental properties in different locations can therefore have different premiums.
This can be particularly important in Newfoundland and Labrador and Nova Scotia, where properties can range from homes in major urban centres to rural and more remote locations.
2. How Much Would the Property Cost to Rebuild?
Insurance companies are interested in replacement cost, not simply what you paid for the property or what it might sell for today.
If a major insured loss destroyed the building, what would it cost to rebuild it?
That can depend on:
- Size of the building
- Construction type
- Labour costs
- Material costs
- Building features
- Demolition and debris removal
- Current construction costs
- Location and accessibility
A property with a higher rebuilding cost will generally require a higher amount of insurance.
And that can affect the premium.
3. What Type of Rental Property Do You Own?
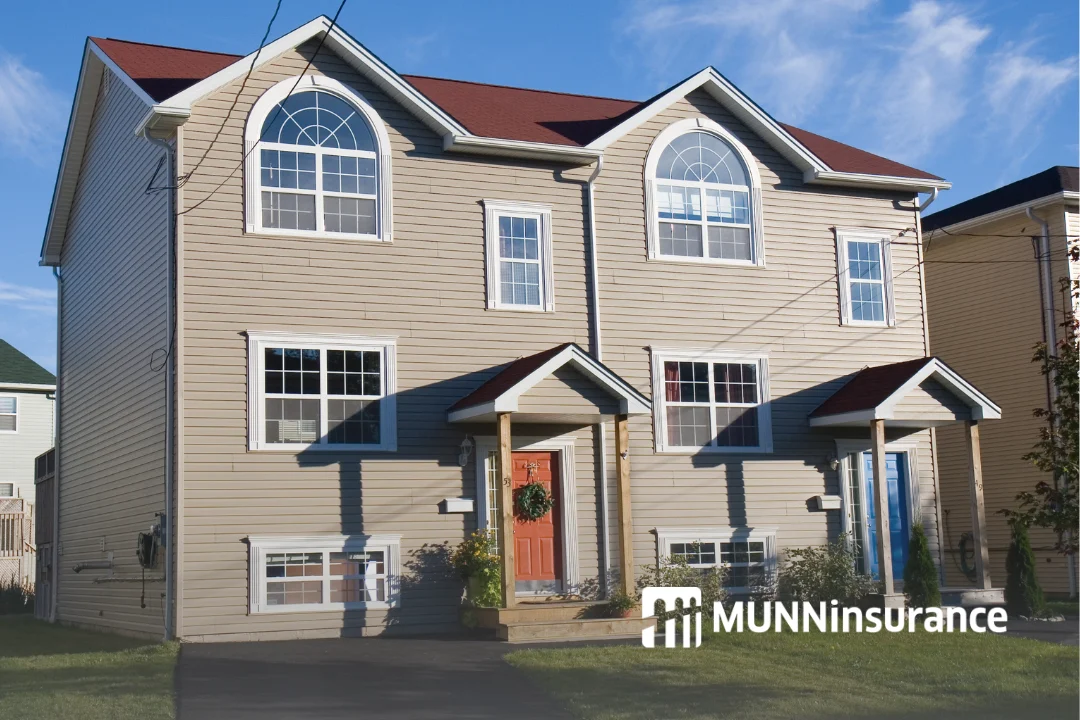
Not all rental properties are the same.
You might own:
- A detached single-family rental home
- A condo
- A duplex
- A triplex
- A multi-unit property
- A basement apartment
- An owner-occupied property with a rental unit
- Several rental properties
The size and complexity of the property can influence the amount and type of coverage required.
A multi-unit building, for example, can present different property, liability and rental income exposures than a single-family rental home.
4. Does the Number of Rental Units Affect the Cost?
It can.
The insurer will generally want to know how many units are in the property and how they are occupied.
More units can mean:
- More tenants
- More kitchens and bathrooms
- Greater potential for water losses
- More rental income at risk
- Additional liability exposure
- Higher rebuilding costs
The number of units is therefore an important part of getting an accurate landlord insurance quote.
5. Does the Age of the Rental Property Matter?
Yes, but age alone does not tell the whole story.
An older rental property may be very well maintained and have updated building systems.
Insurers may want to know about things such as:
- Age and condition of the roof
- Electrical system
- Plumbing
- Heating system
- Oil tank, if applicable
- Renovations and upgrades
- Overall condition of the building
A 50-year-old property with significant updates may present a very different insurance risk from a similar-aged property with original plumbing, electrical and heating systems.
That is why providing accurate information about improvements can be important when getting a quote.
6. Does the Heating System Affect Landlord Insurance Cost?
It can.
The insurer will want to know how the rental property is heated.
That might include:
- Electric heat
- Heat pumps
- Oil heat
- Propane
- Wood-burning appliances
- Other heating systems
Some heating systems or combinations may require additional information.
For example, a property with oil heat may generate questions about the oil tank, while a property with a wood stove may have installation or inspection requirements.
Having these features does not necessarily mean the property cannot be insured. It means the insurer needs the right information to properly assess it.
7. Does the Type of Tenant or Rental Arrangement Matter?
How the property is rented can also affect the insurance.
There can be important differences between:
- Long-term rentals
- Short-term rentals
- Student rentals
- Owner-occupied properties with tenants
- Multi-unit properties
- Properties that are temporarily vacant
If you change how the property is being rented, let your insurance broker know.
A policy arranged for a long-term residential rental should not automatically be assumed to cover every other rental arrangement.
8. Does Vacancy Affect the Price?
Vacancy can affect both the availability and cost of insurance.
An empty property can create additional risk because there may be nobody there to notice a problem quickly.
For example, a:
- Water leak
- Heating failure
- Break-in
- Fire
- Maintenance problem
could go unnoticed for longer.
If a tenant moves out and your rental property will remain vacant, tell your broker.
Depending on the insurer and length of vacancy, there may be changes to the coverage, conditions or premium.
9. Does Claims History Affect Landlord Insurance Cost?
It can.
Insurers may consider previous insurance claims when determining the price and terms of coverage.
The number, type and frequency of previous losses can all be relevant.
For example, a history of repeated water losses may be viewed differently from a property with no claims.
This does not mean one claim automatically makes a property difficult to insure, but claims history is one of the factors an insurer may consider.
10. How Does the Coverage You Choose Affect the Price?
More protection can cost more.
Your landlord insurance premium may be affected by choices involving:
- Amount of building insurance
- Liability limit
- Rental income coverage
- Water damage options
- Sewer backup coverage
- Overland water coverage, where available
- Coverage for landlord-owned property
- Garages, sheds and other structures
- Additional endorsements
- Deductible
This is why comparing landlord insurance based only on price can be misleading.
A lower-priced policy may not provide the same coverage as another option.
The better question is:
What am I getting for the premium I am paying?
Can a Higher Deductible Lower the Cost?
Often, yes.
Your deductible is the amount you are responsible for when a covered claim occurs.
Choosing a higher deductible can reduce the insurance premium in some cases, but it also means taking on more of the cost yourself when you have a claim.
For example, a landlord with several properties and sufficient financial reserves may be comfortable carrying a different deductible than someone who owns their first rental property.
The right choice depends on your situation and how much risk you are comfortable retaining.
Why Can Two Similar Rental Properties Cost Different Amounts to Insure?
Because insurance pricing considers much more than how a property looks from the outside.
Imagine two similar three-bedroom rental homes.
One might have:
- A newer roof
- Updated electrical
- Updated plumbing
- Electric heat
- Good fire protection
- No previous claims
The other might have:
- An older roof
- Original plumbing
- Oil heat
- A more remote location
- Previous water claims
Even if the homes have similar market values, their insurance premiums may be quite different.
That is why online averages can only tell you so much.
Your property details matter.
Is Landlord Insurance More Expensive Than Regular Home Insurance?
It depends.
A rental property presents different risks than a home occupied by its owner.
The property is occupied by tenants, the landlord has less day-to-day control over what happens inside it, there may be additional liability considerations, and rental income may also need to be protected.
The coverage itself can also be different.
Rather than comparing landlord insurance directly with the cost of home insurance, it is more useful to compare landlord insurance options that provide the protection you actually need for a rental property.
Can You Lower the Cost of Landlord Insurance?
There may be ways to manage the cost without simply reducing important coverage.
Keep the Property Well Maintained
Stay on top of the roof, plumbing, heating, electrical systems and other building components.
Preventing losses is better than dealing with them after they happen.
Update Older Building Systems
Updates to electrical, plumbing, heating and roofing can improve the condition of the property and may also affect how insurers view the risk.
Consider Your Deductible
Ask what different deductible options would do to your premium.
Review Your Coverage
Make sure you are paying for coverage appropriate to your property and that important features and structures are accurately reflected.
Tell Your Broker About Improvements
If you have made significant updates, make sure your broker knows.
Review Multiple Properties Together
If you own more than one rental property, talk to your broker about the portfolio as a whole.
There may be different insurance options available as your rental portfolio grows.
What Could It Cost You Not to Have the Right Landlord Insurance?
The cost of landlord insurance is one thing.
The potential cost of not having the right coverage can be much greater.
A rental property can represent hundreds of thousands of dollars in value, an important source of monthly income and a significant part of your overall financial plan.
If something serious happens, you could be exposed to more than just the cost of repairing the building.
A Major Fire or Property Loss
If your rental property is badly damaged by fire or another major insured event, repairs or rebuilding can be extremely expensive.
Without appropriate insurance, you could be responsible for some or all of those costs yourself.
Months Without Rental Income
If tenants cannot live in the property while repairs are being completed, your rental income may stop.
Your expenses may not.
You could still have mortgage payments, property taxes, insurance, utilities and other costs while receiving little or no rent.
Appropriate loss of rental income coverage can be an important part of protecting against that risk.
A Liability Claim
If a tenant, visitor or other person is injured at your property and you are held legally responsible, the financial consequences can extend well beyond a repair bill.
Legal defence costs and damages can be significant.
That is one reason liability coverage is such an important part of landlord insurance.
Damage That Spreads Before Anyone Notices
Rental properties can also experience losses that become much worse if they are not discovered quickly.
A burst pipe, water leak or heating failure in a vacant property, for example, can cause extensive damage before anyone realizes there is a problem.
Having the right insurance does not prevent these events, but it can help protect you financially when an insured loss occurs.
The Wrong Policy Can Also Be a Problem
The risk is not limited to having no insurance at all.
You also want to make sure your insurer knows that the property is being rented and understands how it is being used.
If you have converted a former home into a rental, added units, moved to short-term rentals or made other significant changes, make sure your insurance broker knows.
The goal is to have insurance that accurately reflects the property and the risk.
Think About the Cost of the Risk, Not Just the Premium
When you are comparing landlord insurance, it is natural to focus on the annual price.
But the premium should be considered in the context of what you are protecting.
Your rental property may represent a significant investment. It may generate thousands of dollars in rental income each year. And a serious property or liability loss could have a major financial impact.
The question is not simply:
“How much does landlord insurance cost?”
It is also:
“What could it cost me if I don’t have the right protection when something goes wrong?”
Don’t Shop on Price Alone
Landlord insurance protects a significant asset.
Saving a few dollars on the premium is not much of a bargain if you end up without coverage you thought you had.
When comparing options, ask:
- What is covered?
- What isn’t covered?
- What are the deductibles?
- How much liability coverage do I have?
- Do I have rental income coverage?
- What water damage coverage is included?
- Are my landlord-owned appliances or furnishings covered?
- Are garages and other structures included?
- Are there special conditions I need to follow?
- What happens if the property becomes vacant?
A good landlord insurance quote should help you understand both the price and the protection behind it.
How Can You Get an Accurate Landlord Insurance Quote?
The more accurate the information you provide, the better the insurer can assess the property.
Be prepared to provide details such as:
- Property address
- Number of rental units
- Age of the property
- Building size
- Construction type
- Heating system
- Roof information
- Electrical and plumbing details
- Updates and renovations
- Current occupancy
- Claims history
You do not necessarily need to know every detail before you start.
At Munn Insurance, you can begin with some basic information about your rental property and our team can help gather anything else needed to complete the quote.
The Bottom Line: What Does Landlord Insurance Cost?
It depends on the property.
The cost of landlord insurance in Newfoundland and Labrador and Nova Scotia can be influenced by:
- Where your property is located
- What it would cost to rebuild
- Type and size of property
- Number of units
- Age and condition
- Heating, plumbing and electrical systems
- Occupancy
- Claims history
- Coverage limits
- Deductibles
- Coverage options
That is why the most accurate answer comes from getting a quote based on your rental property and your insurance needs.
And when comparing quotes, don’t look at the premium alone.
Make sure you understand what you are getting for the price.
Find Out What Landlord Insurance Costs for Your Property
There is no need to guess what landlord insurance will cost.
Munn Insurance’s local insurance experts help landlords throughout Newfoundland and Labrador and Nova Scotia find insurance for rental properties of all kinds.
Whether you are buying your first rental property, reviewing the insurance on an existing property or growing your rental portfolio, we can help you understand your options and find coverage that fits.
Get your landlord insurance quote today.
Visit: https://www.munninsurance.com/landlord-insurance-program/
Call: 1-855-726-8627
Protect the property. Protect the income. Protect the investment.
Related News
Recent News
How Much Does Landlord Insurance Cost in Newfoundland and Labrador and Nova Scotia?
If you own a rental property, or are thinking about buying one, there is a good chance you have wondered: How much does landlord insurance cost? The short answer is that there is no single [...]
Are You Paying Too Much for Commercial Auto Insurance? 7 Ways to Help Lower Your Cost
Commercial Auto Insurance is an important cost of doing business if you rely on cars, pickups, vans or trucks to keep your operation moving. But that doesn’t mean you should simply accept whatever premium appears [...]
Fall Checklist for Landlords in Newfoundland and Labrador and Nova Scotia
Fall is one of the best times for landlords to take a close look at their rental properties. The temperatures are dropping, winter weather is coming, and small maintenance issues that are manageable in September [...]