Customer Testimonial: Rick Found Better Cabin Insurance Coverage and Saved About $800
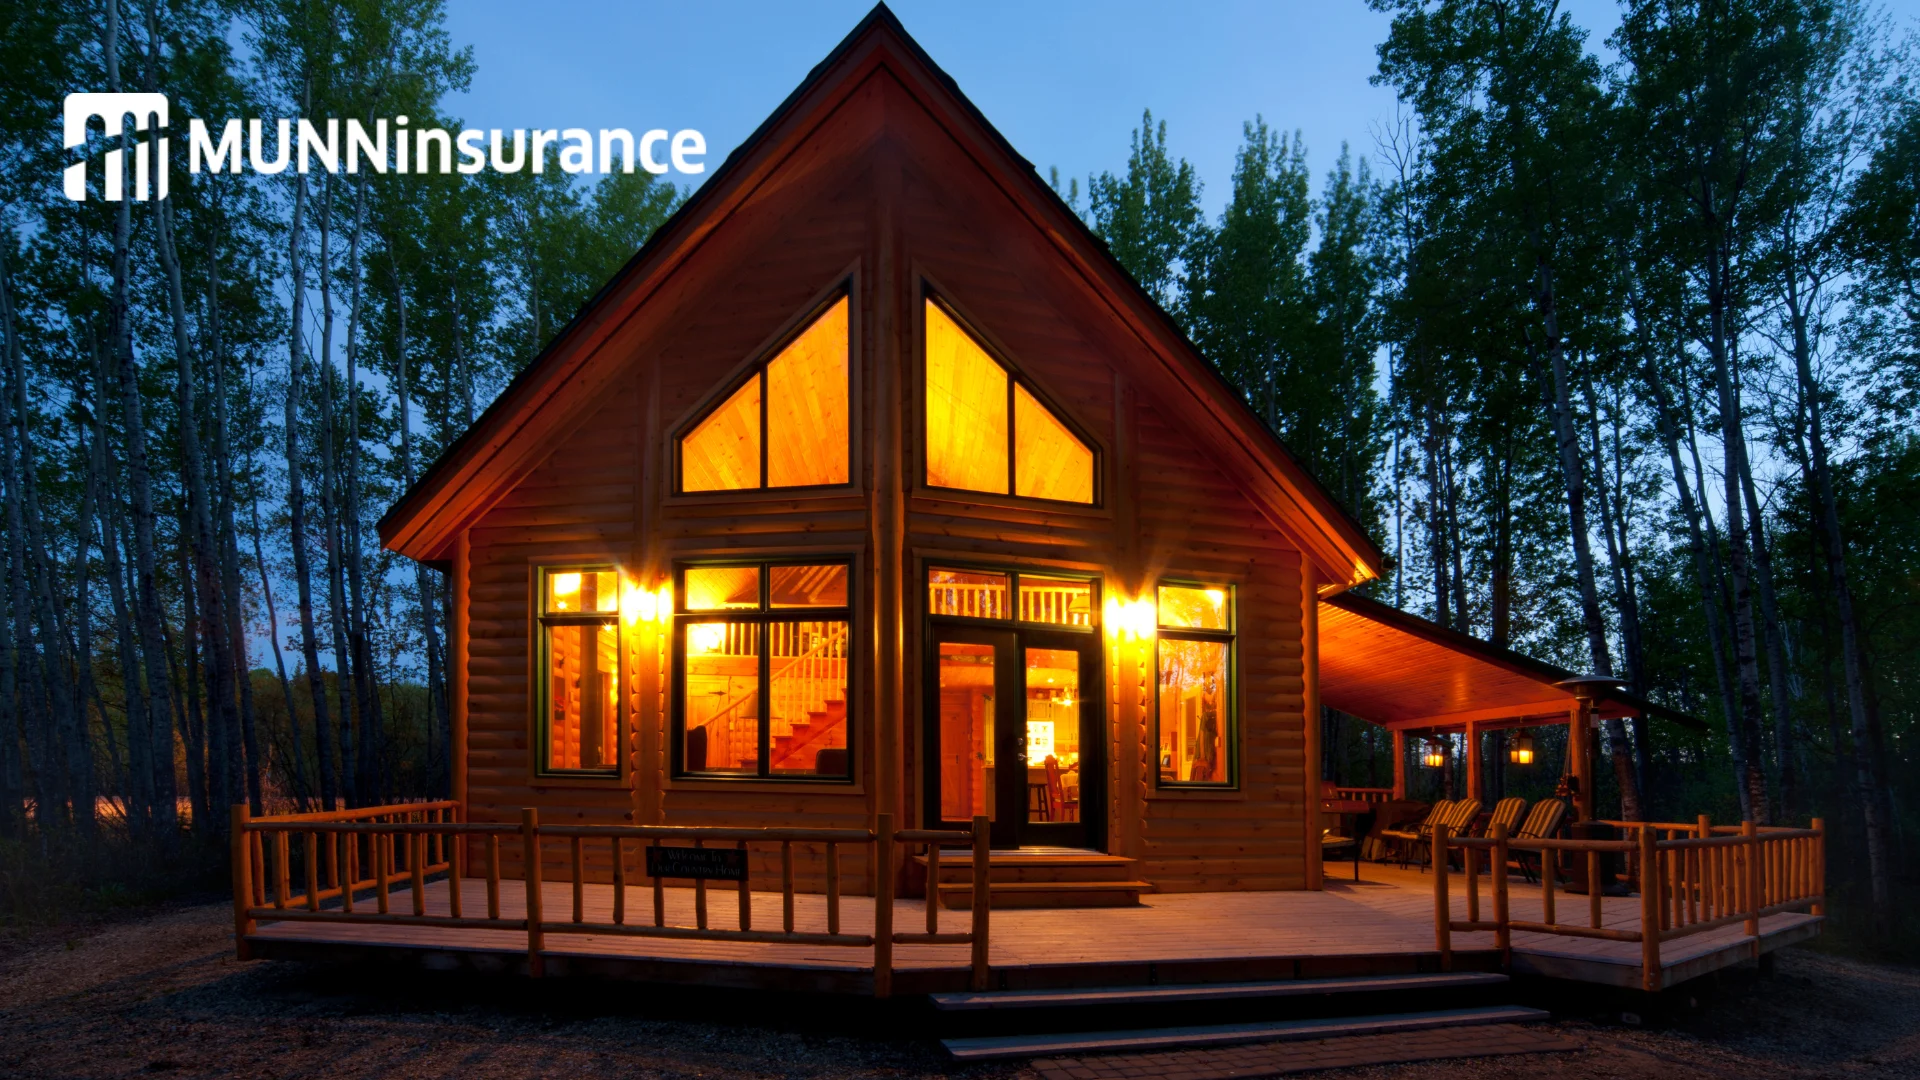
Rick has a beautiful cabin property in Sandy Cove, a stunning part of the province on the Eastport Peninsula.
Like many seasonal property owners, he felt he was paying too much for his insurance. After hearing that a relative had found a better insurance option through Munn Insurance, Rick reached out and asked us to review his seasonal property coverage.
What we found was a real eye-opener.
Rick’s existing policy was with a direct writer. It was costing more than $2,200 per year and, after review, appeared to provide more limited coverage than other options available.
After comparing Rick’s existing policy against other available seasonal home insurance options, we found a new policy that offered broader protection for about $1,400 per year.
That is roughly $800 in annual savings — with stronger coverage in several important areas.
As Rick put it:
“I felt like I was paying too much for my cabin insurance. After hearing that a relative had a better experience through Munn, I decided to ask for a review. I’m glad I did.”
— Rick
One of the biggest differences was the type of coverage.
Rick’s existing direct writer policy appeared to be written on a more limited basis. It was a named perils policy, meaning it only covered the specific causes of loss listed in the policy. It also appeared to settle claims on an actual cash value basis, which means depreciation could reduce the payout after a claim.
That can make a major difference for a cabin, cottage, or seasonal property.
For example, if a cabin has older shingles, siding, flooring, or finishes, an actual cash value settlement may reduce the claim payout because of age and wear. After a serious loss, that could leave the owner with less protection than they expected.
The new recommended option provided several important improvements, including:
- Comprehensive coverage instead of named perils coverage
- Guaranteed replacement cost on the building
- Water damage coverage
- Sewer backup coverage
- Personal property coverage
- Coverage for a shed or outbuilding
- Additional living expense coverage
- A significantly lower annual premium
Rick’s reaction was exactly why these reviews matter:
“I was surprised that the better option was also the cheaper option. I assumed better coverage would automatically mean paying more.”
— Rick
Seasonal homes, cabins, and cottages can be more difficult to insure than a primary residence. Often, direct writers and large national insurance providers simply are not eager to keep these types of policies on their books. Seasonal properties can have different risks, different occupancy patterns, and different underwriting requirements.
But at Munn Insurance, we do want to help with these policies.
We can often provide a stand-alone seasonal insurance policy for your cabin, cottage, or seasonal home. That means we may be able to help even if your home, auto, business, or other insurance is currently placed somewhere else.
That said, we would love to look at the rest of your policies too.
Sometimes reviewing everything together helps uncover savings, coverage gaps, or better ways to structure your insurance. But if your seasonal property is the first thing you want us to look at, we are happy to start there.
Rick summed it up this way:
“I’m glad Munn took the time to actually compare the coverage, not just the price. I feel like I understand what I’m buying now, and I’m getting better protection for less money.”
— Rick
Before renewing your cabin, cottage, or seasonal home insurance, ask yourself:
Do I have comprehensive coverage or named perils coverage?
Is my building insured on actual cash value, replacement cost, or guaranteed replacement cost?
Do I have water damage coverage?
Do I have sewer backup coverage?
Are my outbuildings covered?
Is my personal property limit enough?
Could another insurance company offer better value?
Rick’s real customer story is a great reminder: your renewal may not be your best option.
Better coverage may be available, and it may cost less than you are paying now.
Your seasonal property is more than a building. It is a place for family, memories, and time away. Make sure it is protected properly.
Thinking about renewing your cabin, cottage, or seasonal home insurance? Contact Munn Insurance for a real coverage review before you renew.
We can look at a stand-alone seasonal policy, and if you would like, we can review the rest of your insurance as well.
Related News
Recent News
Employees Use their Personal Vehicles for Work? What Every Business Owner Needs to Know
Using a personal vehicle for work is common. A business owner may use their own pickup to visit customers, carry tools or travel between job sites. An employee may use their personal car to attend [...]
How to Talk to Your Kid About E-Bike and E-Scooter Safety
E-bikes and e-scooters are giving young people more freedom — and putting them into traffic at higher speeds. Here are the conversations parents should be having about helmets, visibility, speed, traffic and safe riding. E-bikes [...]
E-Scooters and E-Bikes Are an Emerging Risk on Our Streets: What Drivers, Parents and Young Riders Need to Know
E-scooters and e-bikes are an emerging risk on our streets, putting more young riders into traffic with cars, trucks and SUVs. They are convenient, fun and increasingly popular. But they can also move surprisingly fast, [...]