
Builder’s Risk Insurance: What Every Homeowner Should Know Before Construction Begins
Building a new home or undertaking a major renovation is an exciting milestone, but it also introduces risks that many homeowners don’t consider until it’s too late. One of the biggest misconceptions in residential construction is that a standard homeowners insurance policy (or the builder’s insurance) will automatically protect the home while it’s being built.
In many cases, that assumption is incorrect.
Builder’s Risk Insurance is a specialized form of property insurance designed specifically for homes and buildings that are under construction. It provides financial protection against unexpected events that can damage the project before it is completed, helping homeowners, builders, and property owners recover from losses that could otherwise be financially devastating.
What is Builder’s Risk Insurance?
Builder’s Risk Insurance, sometimes referred to as Course of Construction Insurance, is a temporary policy that protects a structure while it is being built, renovated, or undergoing significant repairs. Unlike a standard homeowners policy, which is designed for completed and occupied homes, Builder’s Risk Insurance addresses the unique exposures that exist during the construction process.
Coverage typically begins when construction starts and remains in place until the project is completed, occupied, sold, or reaches another milestone outlined in the policy.
What Can Builder’s Risk Insurance Cover?
Coverage varies depending on the insurer and policy wording, but Builder’s Risk Insurance may provide protection for losses resulting from events such as:
- Fire and smoke damage
- Windstorms and hail
- Theft of building materials
- Vandalism
- Certain types of water damage
- Damage caused by vehicles or aircraft
- Materials stored at the construction site and, in some cases, while in transit or stored off-site
The policy is generally intended to protect the building itself, along with materials and supplies that will become part of the completed structure.
Like all insurance policies, exclusions apply. Flood, earthquake, normal wear and tear, faulty workmanship, and mechanical breakdown are commonly excluded unless additional coverage has been purchased.
Who Needs Builder’s Risk Insurance?
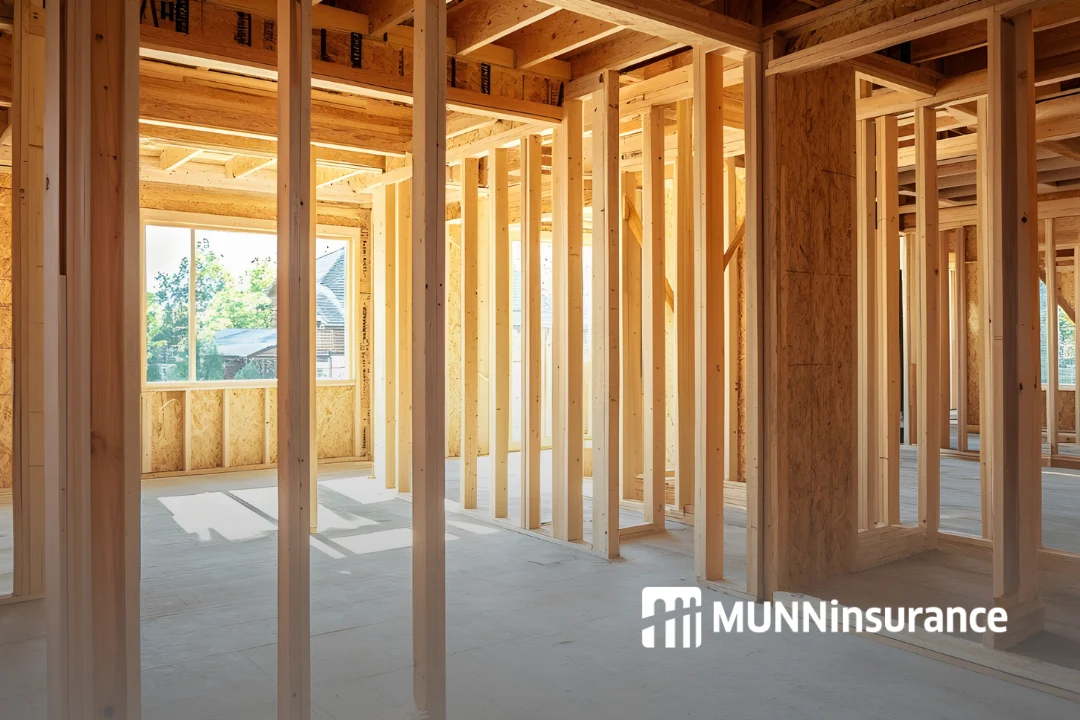
Builder’s Risk Insurance can be an important consideration for a variety of construction projects, including:
- Homeowners building a custom home
- Individuals completing major renovations or additions
- Property investors constructing new homes
- Builders and contractors, depending on the terms of the construction contract
- Developers overseeing residential or commercial projects
One of the most important conversations to have before construction begins is determining who is responsible for arranging Builder’s Risk Insurance. This responsibility is often outlined in the construction contract, but assumptions can lead to costly coverage gaps.
The Biggest Myth: “The Builder Has Insurance, So My Home Must Be Covered.”
This is one of the most common misunderstandings we encounter.
While reputable contractors almost always carry insurance, their coverage is typically designed to protect their business, not necessarily your home.
For example, many contractors carry Commercial General Liability Insurance. This coverage protects them if their operations cause bodily injury or property damage to a third party. It is an essential part of running a construction business, but it is not intended to insure the home under construction or replace materials that are damaged by events such as fire, theft, or severe weather.
Without Builder’s Risk Insurance in place, the financial responsibility for repairing or rebuilding damaged work may not fall where homeowners expect.
The key takeaway is simple: never assume someone else’s insurance is protecting your investment. Always confirm what coverage is in place, who purchased it, and what it includes.
Why a Standard Homeowners Policy Isn’t Enough
Many homeowners are surprised to learn that a traditional homeowners insurance policy is generally designed for homes that are completed and occupied. A partially built home presents entirely different risks than an occupied residence, which is why specialized coverage is often required during construction.
Waiting until the home is complete to think about insurance could leave a significant gap during one of the most vulnerable stages of the project.
Protecting One of Your Largest Investments
For most families, building a home represents one of the largest financial investments they will ever make. Construction projects involve months of labour, materials, planning, and financial commitment. An unexpected loss halfway through a build can delay completion and create substantial out-of-pocket costs if the proper insurance is not in place.
Before construction begins, take the time to understand who is responsible for insuring the project, what coverage is included, and whether additional protection may be needed. Asking these questions early can help prevent costly surprises later and provide peace of mind throughout the building process.
If you’re planning a new build or major renovation and aren’t sure what insurance is required, speaking with a licensed insurance professional before work begins is one of the best investments you can make.
Related News
Recent News
E-Scooters and E-Bikes Are an Emerging Risk on Our Streets: What Drivers, Parents and Young Riders Need to Know
E-scooters and e-bikes are an emerging risk on our streets, putting more young riders into traffic with cars, trucks and SUVs. They are convenient, fun and increasingly popular. But they can also move surprisingly fast, [...]
Does Car Insurance Cover Hitting a Moose or Deer? What Drivers in NL and NS Need to Know
A moose steps onto the highway in front of you. A deer runs out from the side of the road. You have only seconds to react. Wildlife collisions are a very real driving risk in [...]
A New Insurance Benefit for IUOE Local 727 Members: Better Coverage, Service, and Savings
As part of our ongoing commitment to providing value to members, IUOE Local 727 is pleased to introduce a new group insurance benefit. Members now have access to a dedicated Group Home and Auto Insurance [...]